
Insurtech: technological evolution in the insurance world
In October 2020 we published our first analysis of Insurtech in insurance, when the Spanish insurance sector was barely touching 12% digitalization in core processes. Four years later, the map has changed radically: 67% of Spanish insurers already have generative AI pilots in production (Mapfre Economics, 2024), but only 23% manage to scale them beyond the PoC. The problem is no longer “digitalizing”, but rather operationalizing AI with governance, traceability and measurable ROI. This analysis reviews insurtech: the technological evolution of insurance, from paper to reliable AI agents.
The 2026-2027 bottleneck: fragmented data, DORA regulation and scarce talent
Mid-sized insurers (€500M-€5,000M in premiums) share three real pain points that we have validated in 14 BAOSS projects over the past year:
- Claims: 68% of the time is consumed by administrative tasks (classification, extracting data from PDFs, communication with adjusters), not decision-making. The combined ratio suffers by 3-5 points.
- Underwriting: 40% of complex policies require manual review due to a lack of unified historical context. Time-to-quote: 14 days against the 4-hour target.
- DORA/NIS2 compliance: 0% end-to-end visibility of critical technology dependencies (the lesson from the next attack on your company). Potential fines: 2% of annual turnover.
The difference from 2020: tools are no longer missing (GPT, Claude, vLLM, Ollama), what is missing are architectures that make them reliable in production. A naive RAG hallucinates clauses; agents without MCP (Model Context Protocol) cannot access core systems; and fine-tuning without continuous evaluation degrades within weeks, as our analysis of the risk of AI agents already deployed documents.
BAOSS 2026 reference architecture: autonomous agents + hybrid RAG + MCP
Our current Insurtech stack combines three layers that solve the typical failures:
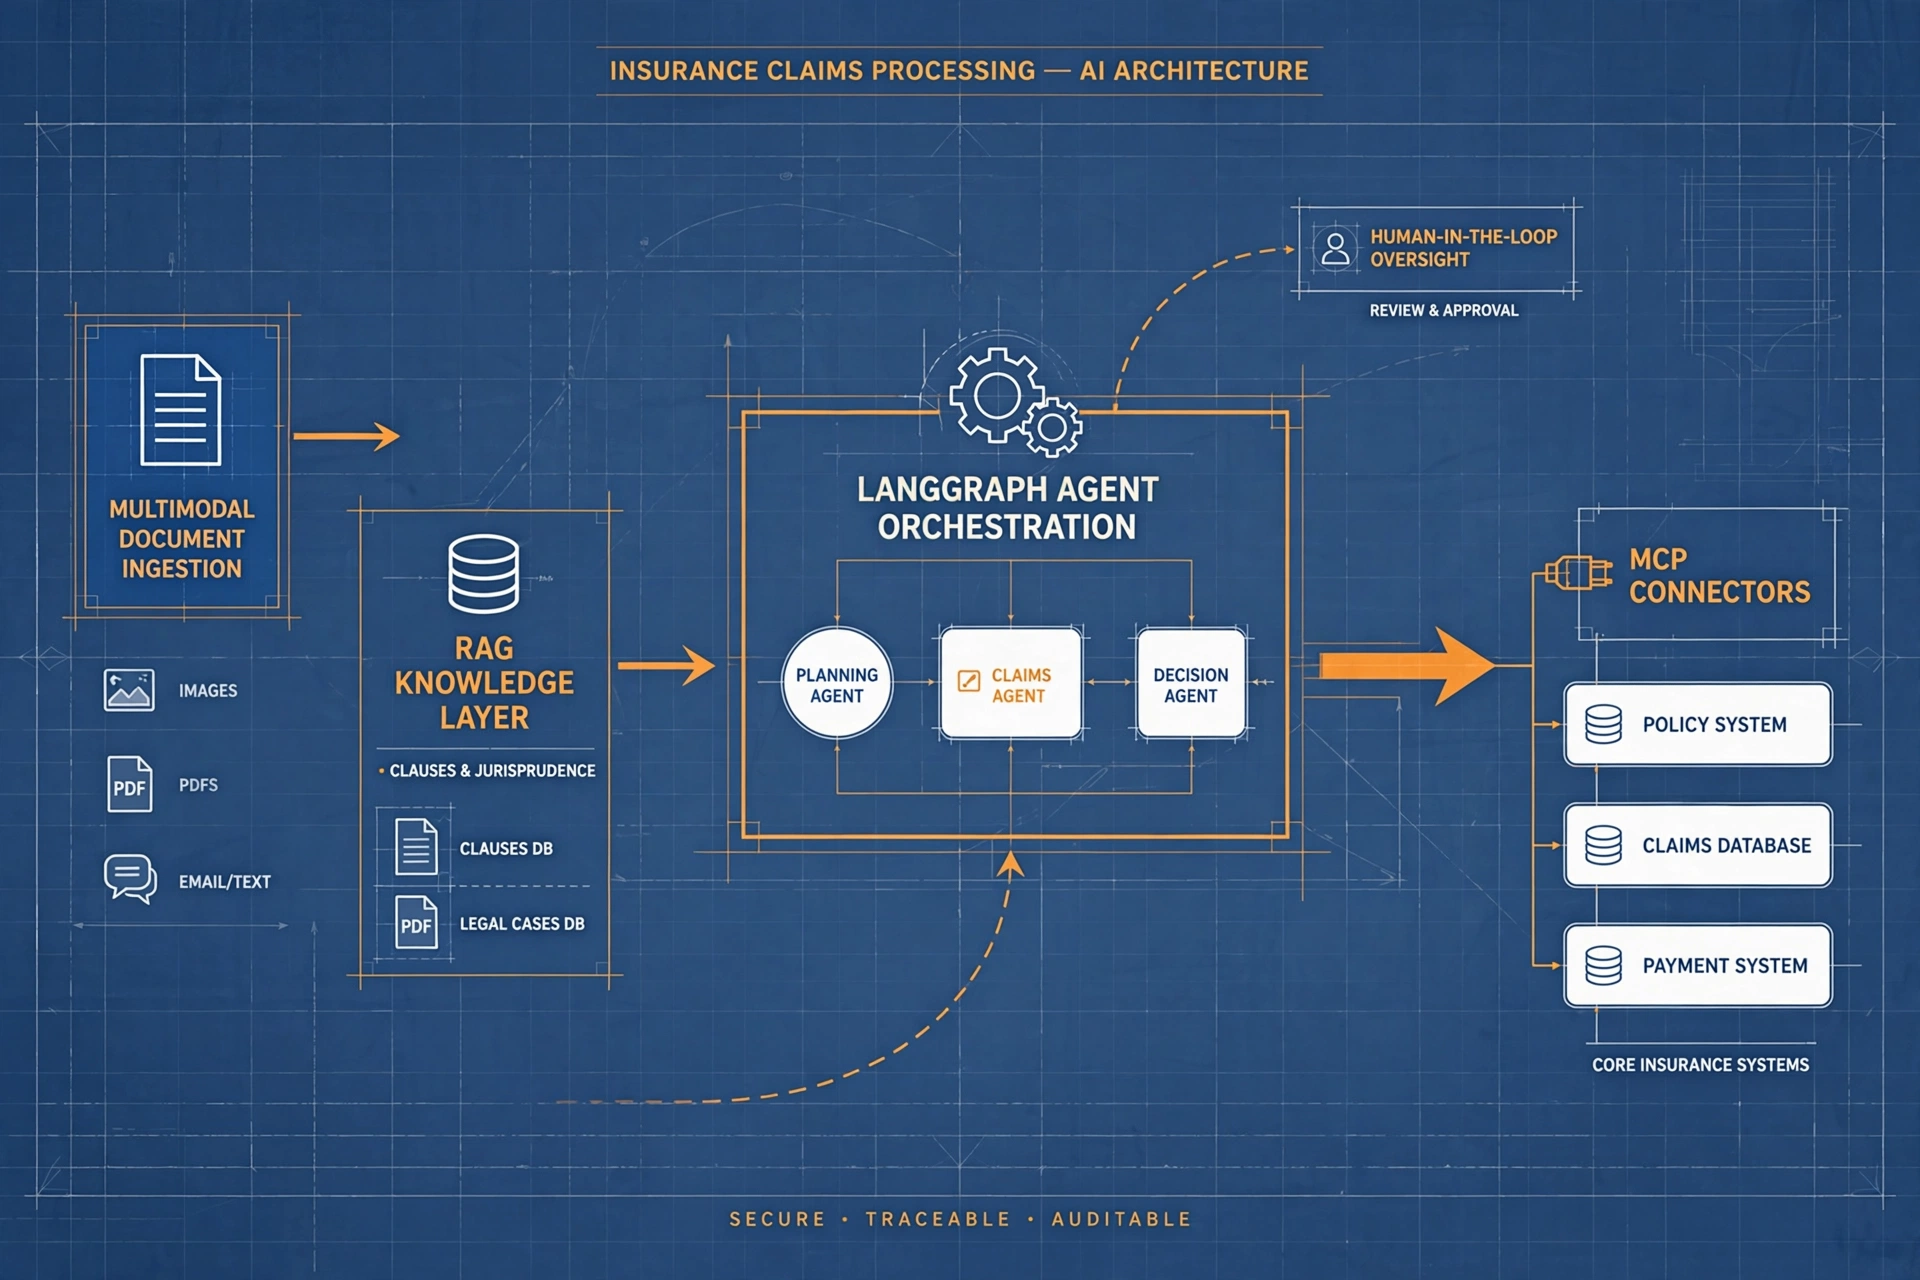
- Knowledge layer (hybrid RAG): Vector DB (Qdrant/Weaviate) + Graph RAG (Neo4j) for clauses, case law and claims history. Semantic chunking + reranking (Cohere Rerank 3.5) + exact citation to PDF page. Reduces hallucinations to below 0.8%.
- Reasoning layer (LangGraph/CrewAI agents): deterministic flows with human-in-the-loop at critical decision points. Each agent exposes MCP servers to connect with Guidewire, Sapiens, Duck Creek or the legacy mainframe via API gateway.
- Observability layer (LangSmith + OpenTelemetry): full prompt→tool→response traceability. Automated nightly evaluation (RAGAS + custom metrics: hallucination rate, citation accuracy, p95 latency).
Why not just GPT? Because an LLM on its own does not know your business. It needs structured context (RAG), the ability to act (tools/MCP) and correction loops (multi-step agents with reflection). We have measured it: RAG alone = 62% accuracy on complex clauses; RAG + reflective agent = 91%.
Real anonymized case: Top-10 Spanish Life/Savings insurer — death claim automation
Context: 12,000 claims/year, 45-day average cycle, 8 FTEs dedicated solely to classifying documentation (death certificates, wills, policies, ID cards).
Deployed solution (12 weeks, 3 sprints)
- Multimodal ingestion: Unstructured.io + OCR (Tesseract + LayoutLMv3) → normalization to canonical JSON.
- Classification agent (LangGraph): 5 specialized nodes (document validator, beneficiary extractor, coverage checker, reserve calculator, communication generator). Each node = versioned prompt + curated few-shots + MCP tool to the core.
- Selective human-in-the-loop: only escalated to a handler if confidence < 0.92 or amount > €150k. 78% of cases are resolved without human touch.
- Continuous evaluation: golden dataset of 500 cases. Weekly metrics in LangSmith. Automatic rollback if F1 < 0.88.
Results at 6 months (real production, not PoC)
- Average cycle: 45 → 11 days (-76%).
- FTEs freed up: 6.2 → reassigned to complex case management and support for vulnerable people.
- Combined ratio on life claims: -2.3 points.
- ROI: 3.8x in 8 months (total project cost: €340k against €1.3M/year in recurring savings).
- DORA compliance: 100% traceability decision→data→model.
Technical key: we do not do fine-tuning. We use hybrid RAG + structured prompting + continuous evaluation. Less cost, more control, and auditable by the regulator.
Real anonymized case: SME broker — multi-line commercial underwriting in hours, not weeks
Context: 3,500 policies/year between new and renewals. Questionnaires of 40+ questions, data scattered across CRM, emails and insurer portals. Time-to-bind of 14 days. Loss of 22% of opportunities due to slowness.
Agent architecture (CrewAI + MCP + local vLLM)
- “Risk Profiler” agent: connects via MCP to CIRBE, INE, Cadastre, commercial registries and its own claims history. Generates a structured risk profile in 90 seconds.
- “Policy Matcher” agent: RAG over 1,200 products from 12 insurers (clauses, exclusions, appetite). Recommends the 3 optimal ones with traceable justification.
- “Document Generator” agent: fills in questionnaires, generates DIP, IPID and contracts. Validates cross-consistency (sums insured vs. risk value).
- Human review: the broker validates the final recommendation. The agent learns from corrections (preference learning via DSPy).
Metrics at 4 months post-go-live
- Time-to-quote: 14 days → 3.2 hours (-98%).
- Conversion rate: 68% → 84% (+16 points).
- Underwriting errors (post-bind endorsements): -63%.
- Infrastructure cost: €0.12/policy (vLLM on own GPU, zero token cost).
- Broker satisfaction (NPS): +31 points.
Strategic decision: local models (Llama-3.1-70B-Instruct via vLLM/Ollama) for sensitive data. Zero data egress, p95 latency of 1.8s and DORA compliance by design.
The 2026 Insurtech ecosystem: from comparators to “AI as an insurance service”
The players we cited in 2020 (Rastreator, Wefox, Coverfy, Klinc) have pivoted or consolidated. The new 2026-2027 wave is not marketplaces, but specialized AI platforms:
- Shift Technology / Tractable / ControlExpert: computer vision + LLM for auto/home loss assessment. They process 40M+ claims/year globally.
- Zelros / Akur8 / Earnix: AI-native pricing & underwriting, integrated via API into core systems.
- Neos / Wrisk / Laka: full-stack digital MGAs with AI embedded in the product (pay-per-use, behavioral).
- Vertical AI-first insurtechs: Cytora (commercial), Planck (data), Atidot (life), Digital Fineprint (SME).
In Spain, Mapfre Insur_space, Wayra (Telefónica) and Startupbootcamp Insurtech accelerate startups with real traction (ARR > €500k), not just slide decks. Corporate-startup collaboration has matured: paid PoC in 8 weeks → framework agreement if KPIs are met.
Technical checklist for your 2026 roadmap (validated across 14 deployments)
- [ ] Data inventory + quality: do you have a unified catalog of clauses, claims and policies? Documented lineage? (Prerequisite for a reliable RAG.)
- [ ] Use cases prioritized by ROI, not by hype: high-frequency/low-complexity claims > complex underwriting > customer service.
- [ ] MCP-first architecture: expose core systems as MCP servers. Avoid the spaghetti of ad-hoc connectors.
- [ ] Evaluation before model: define the golden dataset, business metrics (not just accuracy) and CI/CD for prompts.
- [ ] AI governance from day 1: model registry, risk assessment (EU AI Act), human oversight and rollback plan.
- [ ] Hybrid talent: you need AI Engineers (not just data scientists) who master LangGraph, RAG, evals and GPU infrastructure.
- [ ] Measurable quick win < 12 weeks: document classifier, clause extractor or coverage recommender. Proves value and buys license.
Errors that keep killing Insurtech AI projects (and how we avoid them)
- “We bought Copilot/ChatGPT Enterprise and that’s it” → without your own RAG, it hallucinates clauses. Solution: hybrid RAG + continuous evaluation.
- “We fine-tune Llama with our PDFs” → catastrophic: it forgets the base knowledge, it is expensive and opaque. Solution: RAG + prompting + few-shots. Fine-tune only if you have > 100k curated examples and the evals show a gain > 5 points.
- “Autonomous agents without brakes” → regulatory and reputational risk. Solution: LangGraph with interrupt nodes + policy engine (OPA) + immutable audit trail.
- “Data in the public cloud without sovereignty” → DORA/NIS2 forbids it for critical systems. Solution: on-prem or hybrid vLLM/Ollama + sovereign GPU (AWS EU Sovereign Cloud, Azure EU, local providers).
- “An IT project, not a business project” → no KPIs for claims, conversion or cost. Solution: business/IT co-ownership from the kickoff, with shared OKRs.
The next 18 months: trends we are already implementing
- Multi-organization agents (A2A): broker ↔ insurer ↔ reinsurer ↔ adjuster exchanging context via standardized MCP. The Agent-to-Agent protocol is emerging and will be the next standard.
- Data sovereignty as a competitive advantage: insurers that keep their models and data on sovereign infrastructure will earn the trust of both regulator and customer.
- From automation to self-learning: agents will move from executing rules to refining their own policies with continuous evaluation and preference learning, always under human supervision.
Conclusion on insurtech: the technological evolution of insurance
The technological evolution of the insurance world is no longer a matter of choosing between one comparator and another. It is a deep transformation: from processing documents to processing decisions, with reliable, traceable and governed AI agents. The sector that masters the reasoning layer —not the one with the most tools— will be the one that wins margin, trust and market share.
At BAOSS we have 14 Insurtech deployments in production with audited metrics: claims from 45 to 11 days, underwriting from 14 days to 3.2 hours and DORA compliance by design. We do not sell tools; we sell architectures that work: that is BAOSS, the operating system for business agents.
Request your AI diagnosis for insurers and discover the real ROI of your digitalization →
Prefer to talk to us directly? Contact the BAOSS team and tell us about your challenge.